In the Lone Star State, where businesses thrive and employees’ financial well-being is a top priority, the employee retirement income security act (ERISA) Bond plays a pivotal role. The ERISA Bond, or Employee Fidelity Bond, is an essential safeguard for employee benefit plans, ensuring the protection of retirement and health plan assets. In this article, we will delve into the significance of the ERISA Bond in Texas, its purpose, and how it safeguards the interests of both employers and employees.
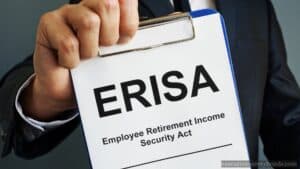
ERISA, a federal law, establishes standards and regulations for employer-sponsored benefit plans, including retirement and health plans. In texas, as in the rest of the United States, the ERISA Bond is a critical component of ERISA compliance. This bond ensures the security of plan assets and guarantees that employers and plan fiduciaries act in the best interests of plan participants.
The ERISA Bond functions as a form of insurance that protects employee benefit plans from losses resulting from fraudulent or dishonest acts by plan officials and employees. These acts can include theft, embezzlement, misappropriation, or any other financial misconduct that could compromise the assets of the benefit plan.
In texas, employers and plan administrators subject to ERISA regulations are required to obtain an ERISA Bond. The bond amount is typically equal to at least 10% of the total plan assets, with a minimum coverage amount of $1,000 and a maximum set by federal regulations. This bond provides financial recourse in case of fiduciary breaches, ensuring that participants and beneficiaries receive the benefits they are entitled to.
The ERISA Bond is designed to safeguard the interests of employees who rely on their benefit plans for retirement security, healthcare coverage, and other essential benefits. By requiring employers and plan fiduciaries to obtain this bond, Texas ensures that the financial well-being of employees is protected against unscrupulous actions that could jeopardize their benefits.
Additionally, the ERISA Bond helps maintain the integrity of employee benefit plans, instilling confidence in employees and plan participants that their hard-earned benefits are secure and will be available when needed.
In Texas, the ERISA Bond is more than just a regulatory requirement; it’s a fundamental aspect of protecting the financial interests of employees and ensuring the sound management of benefit plans. By holding employers and plan fiduciaries accountable and providing a safety net for plan assets, the ERISA Bond plays a vital role in safeguarding the retirement and health benefits of countless Texans.
As Texas continues to be a hub for businesses and innovation, the ERISA Bond remains a critical tool in upholding the highest standards of employee benefit plan management, ensuring that the state’s workforce enjoys financial security and peace of mind for years to come. It’s not just a bond; it’s a testament to Texas’ commitment to securing employee benefits.
No, the primary purpose of the ERISA Bond is to provide financial protection for employee benefit plans and their participants in case of dishonest or fraudulent acts by plan officials or employees. It is not intended to cover legal expenses or fines resulting from fiduciary breaches or legal disputes. Employers and plan fiduciaries typically need to secure separate liability insurance or legal representation to address legal matters related to ERISA compliance and fiduciary responsibilities.
While the ERISA Bond requirements are generally based on the total plan assets, including those of small businesses or startups, there may be some flexibility in bond amounts for smaller plans. Employers should consult with a qualified ERISA expert or legal advisor to determine the appropriate bond amount based on their specific plan and circumstances. However, even small plans are subject to ERISA regulations and are typically required to obtain the bond to protect plan participants.
Each employee benefit plan with distinct plan assets and fiduciaries typically requires its own separate ERISA Bond. While an employer may offer multiple plans, each plan operates independently, and the bond is designed to protect the assets of each specific plan. Combining plans under a single bond may not provide adequate protection for each plan’s assets and participants, and it could result in non-compliance with ERISA regulations. Employers offering multiple plans should consult with ERISA experts or legal advisors to ensure compliance and appropriate bond coverage for each plan.


Axcess Surety is the premier provider of surety bonds nationally. We work individuals and businesses across the country to provide the best surety bond programs at the best price.